•
Other recommended articles
See All

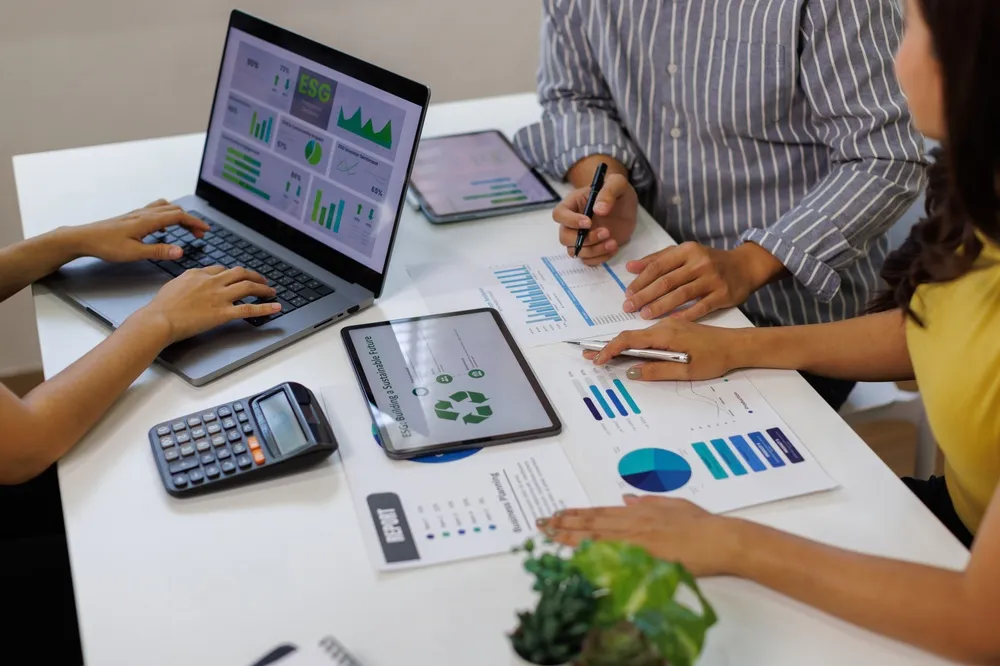
Since the issuance of POJK No. 51/POJK.03/2017 on the Implementation of Sustainable Finance for Financial Services Institutions, Issuers, and Public Companies, the preparation of Sustainability Reports has become part of corporate disclosure practices in Indonesia. However, the diversity of reporting frameworks in use has made sustainability information difficult to compare across companies. At the global level, the need for a uniform standard was addressed by the International Sustainability Standards Board (ISSB) through the IFRS Sustainability Disclosure Standards, namely IFRS S1 and IFRS S2.
In line with this development, the Sustainability Standards Board of the Institute of Indonesia Chartered Accountants (DSK IAI) ratified the Sustainability Disclosure Standards (SPK) on 1 July 2025, comprising PSPK 1 on General Requirements for Disclosure of Sustainability-related Financial Information and PSPK 2 on Climate-related Disclosures. Both standards, which adopt IFRS S1 and IFRS S2, take effect on 1 January 2027, with early application permitted for entities that are ready. The standards were launched jointly with Bank Indonesia, the Ministry of Finance, and the Financial Services Authority (OJK), making Indonesia one of 33 jurisdictions to have implemented the global sustainability reporting framework.
PSPK 1 sets out the conceptual foundations of disclosure, including fair presentation, materiality, the reporting entity, and connected information to financial report. PSPK 1 applies to sustainability related risks and opportunities in general, while PSPK 2 focuses specifically on climate-related risks and opportunities. Both share the same four core content areas: (1) governance, covering oversight of sustainability matters by the company's governing bodies; (2) strategy, covering the impact of risks and opportunities on the business model; (3) risk management, covering the processes for identifying, assessing, and monitoring risks; and (4) metrics and targets, covering performance measures and the targets set. The key distinction of these standards is the requirement that sustainability information be clearly connected to the figures in the financial statements.
Under PSPK 2, companies are required to disclose the impact of physical and transition climate risks on their business model, value chain, and financial performance, including the resilience of their strategy under various climate scenarios. Companies must also disclose their Scope 1, 2, and 3 greenhouse gas (GHG) emissions. For financial services institutions, Scope 3 emissions include financed emissions, namely emissions arising from the business activities of borrowers and investment portfolios.
The implications of these standards extend beyond reporting companies to businesses across the value chain. As large companies and financial institutions need to report their value chain emissions, demand for data from suppliers, business partners, and borrowers will increase. Businesses that already record their energy use, map their climate risks, and have a designated person responsible for sustainability matters will be better prepared to meet these needs. Furthermore, such readiness can open broader access to sustainable financing and strengthen the trust of business partners and investors. The scope of entities required to apply these standards will follow the provisions of the relevant authorities.
Uniform and measurable disclosure standards also play an important role in preventing greenwashing. With comparable metrics connected to financial statements, corporate sustainability claims can be assessed more objectively by stakeholders.
As a financial services institution, BCA continues to strengthen its sustainability disclosures, including climate-related disclosures, in line with developments in national and global standards. At the same time, BCA supports its customers in transitioning toward a low-carbon economy through sustainable financing. Discover BCA's sustainability disclosures in the 2025 Sustainability Report at https://pustaka.bca.co.id/ESG/2026/File/20260212-SR25-BCA-EN.pdf
The implementation of PSPK 1 and PSPK 2 marks a new chapter in which sustainability information stands on equal footing with financial information. Preparing early is no longer an option, but a strategic step for companies seeking sustainable growth and global competitiveness.
#BCAforSustainability
Source: Adapted from various sources.